Curious about how much auto insurance costs in the Bay State? You’ve come to the right place! In this comprehensive guide, we’ll delve into the intricacies of auto insurance rates in Massachusetts, providing you with a clear understanding of what factors influence these rates, average costs, and much more. Get ready to embark on a journey through the world of auto insurance in Massachusetts.
At Backlinko, we believe that knowledge is power. Gaining insights into your auto insurance options and costs not only empowers you but also helps you make informed decisions. So, let’s dive into the heart of Massachusetts auto insurance, uncovering everything from factors affecting rates to the impact of legislative changes.
Factors Influencing Auto Insurance Rates in Massachusetts
Ever wondered why your auto insurance rates in Massachusetts seem to be all over the place? You’re not alone. The reality is that numerous factors can significantly sway your premium costs.
It’s not just about how much you drive or your vehicle’s make and model. Multiple variables come into play, each with its own impact on how much you pay. Let’s dive into what determines your rates and see just how these elements stack up.
Primary Factors Affecting Your Insurance Premiums
Your driving record is one of the biggest influencers of auto insurance rates. A clean slate can mean lower rates, while accidents or violations can send them soaring. Another critical factor is your insurance history; if you’ve been consistently covered without lapses, you’re likely to snag a better deal.
But that’s just the start. The type of car you drive matters, too. High-performance vehicles or those prone to theft typically cost more to insure. And don’t forget about your coverage level—opting for a higher deductible can bring your monthly payments down.
Additional Variables Impacting Premium Costs
Beyond the primary factors, a series of additional variables can tweak your insurance rates:
- Age and gender
- Marital status
- Credit score
- Annual mileage
- Type of usage (personal vs. business)
- Available safety features in your car
Pro Tip: Bundling your auto insurance with other policies, like home insurance, can save you a substantial amount. Always check for multi-policy discounts!
Impact of Geographic Location Within Massachusetts
Your ZIP code isn’t just a number; it’s a significant factor in determining your auto insurance rates in Massachusetts. Urban areas usually come with higher premiums due to increased traffic risks, more accidents, and the likelihood of theft.
Here’s the deal: Insurers evaluate the frequency of claims in your area, along with repair costs and other local risks. Living in a city like Boston could mean facing higher rates compared to a smaller town with fewer incidents.
| Geographic Factor | Potential Impact on Rates |
|---|---|
| Urban vs. Rural | Increased rates in urban areas |
| Crime Rates | Higher crime leads to higher premiums |
| Weather Patterns | Areas prone to extreme weather may see higher rates |
Average Auto Insurance Costs in Massachusetts
Did you know that Massachusetts drivers pay some of the highest insurance premiums in the country? It’s true, and if you’re a Bay State resident, you might be wondering how your rates stack up.
Let’s break down the average costs of auto insurance in Massachusetts and see how they compare against the national average. This’ll give you a clear picture of where your premiums land on the spectrum.
Massachusetts vs. National Average Rates
On average, Massachusetts drivers shell out around $1,460 per year for auto insurance. How does that compare to the national average? Well, the national average is about $1,300. So, Massachusetts drivers are paying a premium of approximately $160 more each year.
Here’s the deal: certain vehicles cost more to insure. For instance, a sedan typically costs about $1,420, while an SUV could set you back $1,500. If you’re driving a sportier model, expect to pay even more.
Pro Tip: Want to save on your insurance? Consider bundling your auto policy with home insurance for potential discounts.
Historical Trends in Massachusetts Insurance Costs
Insurance rates have fluctuated over the past decade, and tracking these trends can give you insights into what to expect. Here’s a look at how rates have changed:
- 2013: Average cost was $1,200
- 2015: Rates climbed to $1,250
- 2017: Saw a jump to $1,300
- 2019: Rates increased to $1,350
- 2021: Peaked at $1,400
- 2023: Holding steady at $1,460
Average Costs by City in Massachusetts
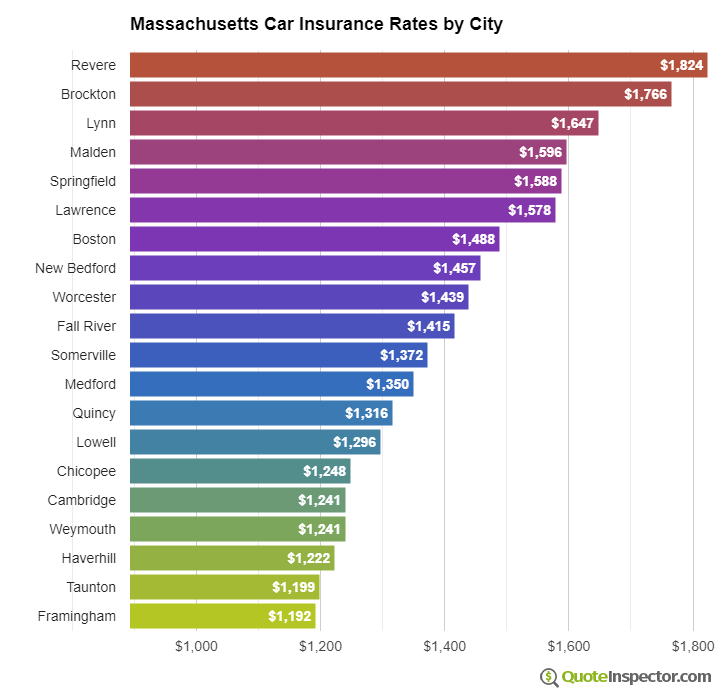
Not all Massachusetts cities are created equal when it comes to auto insurance rates. Here’s a quick comparison to see how costs vary from one city to another:
| City | Average Annual Cost |
|---|---|
| Boston | $1,700 |
| Springfield | $1,550 |
| Worcester | $1,470 |
| Cambridge | $1,480 |
| Lowell | $1,430 |
Types of Auto Insurance Coverage Available in Massachusetts
Ever wondered what types of auto insurance coverages are available in Massachusetts? You’re not alone. Choosing the right coverage can be a game-changer in protecting yourself financially after an accident.
Massachusetts law requires drivers to carry specific minimum coverages, but that’s just the beginning. While the state-mandated coverages ensure you meet legal requirements, optional policies can offer greater peace of mind.
Mandatory Coverage Requirements in Massachusetts
In Massachusetts, drivers must adhere to certain minimum auto insurance requirements. These include:
- Bodily Injury to Others: At least $20,000 per person and $40,000 per accident.
- Personal Injury Protection (PIP): A minimum of $8,000 per person.
- Bodily Injury Caused by an Uninsured Auto: At least $20,000 per person and $40,000 per accident.
- Damage to Someone Else’s Property: A minimum of $5,000.
These coverages ensure basic protection. BUT here is the deal: meeting only the minimum requirements might leave you exposed to significant out-of-pocket costs after a more serious accident.
Optional Coverage Choices
Want to go beyond the basics? Consider optional coverages to bolster your protection.
Some popular choices include Comprehensive Coverage and Collision Coverage. Comprehensive covers non-collision-related incidents like theft or natural disasters. Collision pays for damages from accidents, regardless of fault.
Pro Tip: Opt for Uninsured Motorist Coverage if you want extra security against drivers who fail to maintain insurance.
Additional options worth exploring are Medical Payments Coverage and Rental Reimbursement. These cover medical expenses and temporary transportation costs, respectively, after an accident.
Comparison: Basic vs. Optional Coverage
Let’s stack basic and optional coverage options side by side:
| Coverage Type | Basic Coverage | Optional Coverage |
|---|---|---|
| Bodily Injury to Others | $20,000/$40,000 | Increased limits |
| Personal Injury Protection (PIP) | $8,000 | Extended benefits |
| Property Damage | $5,000 | Higher limits |
| Uninsured Motorist | $20,000/$40,000 | Enhanced protection |
| Comprehensive | Not included | Available |
| Collision | Not included | Available |
| Medical Payments | Not included | Available |
| Rental Reimbursement | Not included | Available |
Choosing between basic and optional coverages ultimately depends on your financial situation and risk tolerance. By understanding these options, you can make an informed decision that best suits your needs.
Discounts and Savings Opportunities for Massachusetts Drivers
Did you know that many Massachusetts drivers overpay on their car insurance without realizing it? That’s right! There are countless discounts and savings opportunities just waiting to be claimed.
Here’s the deal: insurance companies offer a variety of discounts to help you reduce your premiums, but you need to know where to look and how to qualify. Understanding the available discounts and eligibility criteria is crucial to maximizing your savings.
Types of Discounts Available
Massachusetts insurers provide several options for reducing your insurance costs. These can range from safe driver discounts to bundling policies. Let’s break down some of the most common discounts:
- Safe Driver Discount: If you’ve maintained a clean driving record with no accidents or violations, you could qualify for a safe driver discount.
- Multi-Policy Discount: Bundle your auto insurance with homeowner or renter insurance to save even more.
- Good Student Discount: Students with a high GPA can often snag a discount, as insurers view them as lower risk.
- Low Mileage Discount: Drive less, pay less. If you don’t use your car frequently, your insurer might offer a lower rate.
- Defensive Driving Course Discount: Completing an approved course can earn you a discount. Plus, it sharpens your driving skills!
Eligibility Criteria for Discounts
Before you cash in on these discounts, you need to meet certain criteria. Here’s what you’ll need:
- For a Safe Driver Discount, you’ll typically need a clean driving record for at least 3-5 years.
- To qualify for a Multi-Policy Discount, you must have two or more policies with the same insurer.
- Good Student Discounts often require a GPA of 3.0 or higher.
- The Low Mileage Discount usually applies if you drive less than 7,500 miles per year.
- Completion of a certified course is necessary for a Defensive Driving Course Discount.
Strategies to Qualify for Multiple Discounts
Stacking discounts can lead to serious savings. Here’s how you can qualify for multiple discounts:
- Maintain a clean driving record to ensure you are eligible for a Safe Driver Discount.
- Bundle your insurance policies under one insurer to take advantage of the Multi-Policy Discount.
- If you’re a student, keep your grades up to access the Good Student Discount.
- Consider taking public transport or carpooling to reduce your mileage and qualify for a Low Mileage Discount.
- Enroll in a defensive driving course to potentially unlock additional savings.
Case Study: Jane from Boston shaved off $300 from her yearly premium after combining a safe driver discount, a multi-policy discount, and a low mileage discount. Now that’s smart savings!
Pro Tip: Always ask your insurer about any new or lesser-known discounts they might offer. Sometimes, just asking the right questions can open doors to unexpected savings!
Influential Insurance Providers in Massachusetts

Did you know that not all insurance providers are created equal? Some offer stellar service, while others might leave you frustrated.
In Massachusetts, several major players dominate the auto insurance market. Let’s dive into who they are and what they offer.
Major Insurance Providers and Their Reputation
When choosing an insurance provider, reputation matters. In Massachusetts, Liberty Mutual, GEICO, and Progressive are household names. They each have their pros and cons. Liberty Mutual is known for its wide coverage options but can be pricey. GEICO often scores high for affordability but might lack personalized service. Progressive is celebrated for its innovative services but has mixed reviews on claims processing.
Customer Satisfaction and Reviews
Customer satisfaction can make or break your experience with an insurer. According to recent surveys, Amica Mutual consistently ranks at the top for customer satisfaction. Meanwhile, State Farm is praised for its local agents and personal touch. BUT here’s the deal: what works for one driver might not work for another. So, it’s critical to read reviews and ask around.
Variety of Coverage Plans
Each provider offers a different suite of coverage options. Liberty Mutual, for example, provides customized coverage options that allow you to adjust your deductible and coverage limits. GEICO offers a no-frills basic plan that is perfect if you’re on a budget. Progressive stands out with its Snapshot program, rewarding safe driving behaviors with discounts.
It’s important to understand what each insurer offers before making your decision.
| Provider | Contact Details | Customer Reviews | Unique Features |
|---|---|---|---|
| Liberty Mutual | Phone: 1-800-290-7933 | 3.8/5 stars, praised for coverage options | Customizable plans |
| GEICO | Phone: 1-800-207-7847 | 4.1/5 stars, known for affordability | Basic plan options |
| Progressive | Phone: 1-888-671-4405 | 3.9/5 stars, mixed claims reviews | Snapshot program |
| Amica Mutual | Phone: 1-800-242-6422 | 4.4/5 stars, excellent customer service | High customer satisfaction |
| State Farm | Phone: 1-800-782-8332 | 4.0/5 stars, good personal service | Local agents |
Pro Tip: Don’t just go with the cheapest provider. Consider customer reviews and satisfaction ratings to ensure a smooth claims process.
The Impact of Legislative Changes on Auto Insurance in Massachusetts
Did you know that legislative changes can shake up your auto insurance premiums overnight? Massachusetts is a prime example where new laws are frequently rewriting the rulebook for drivers.
The state is no stranger to implementing new regulations that can significantly affect how much you pay for auto insurance. Whether it’s through safety mandates or requirements for more comprehensive coverage, these changes have a direct line to your wallet.
Recent Legislative Changes and Their Influence
Recent legislative changes have redefined how premiums are calculated in Massachusetts. The introduction of new safety regulations has prompted insurers to rethink risk assessments.
- 2021 Safety Mandate: Required advanced safety features in new cars, potentially lowering premiums for compliant vehicles.
- 2022 Environmental Incentive: Discounts introduced for electric and hybrid vehicles, encouraging greener options.
- 2023 Data Privacy Law: Restricted the amount of driver data insurers can use, leading to more generalized premium calculations.
How These Changes Affect Premium Calculations
Here’s the deal: each legislative update can cause premiums to be recalculated, often pushing them up or down depending on the specifics. For example, the 2021 Safety Mandate means that if you’ve got a vehicle loaded with safety features, your premium could drop significantly. But if your ride is older and lacks these updates, you’re likely to see a bump in your costs.
Pro Tip: Always stay updated on new laws. They can offer hidden savings opportunities!
Future Legislative Proposals and Their Expected Impact
Looking forward, there are several proposals on the horizon that could further alter the insurance landscape. Imagine a world where even more incentives are provided for clean energy vehicles.
- Green Vehicle Initiative: Proposed additional tax breaks and premium reductions for electric vehicles, aiming to cut emissions and reduce costs for eco-friendly drivers.
- Telematics Expansion: Expanding the use of telematics could lead to more personalized premiums, rewarding safe driving habits.
These proposals could pave the way for a more cost-effective and environmentally-friendly driving experience in Massachusetts.
Conclusion
In conclusion, understanding how much auto insurance is in Massachusetts involves a deep dive into various factors, costs, and coverage options. By staying informed and leveraging the available discounts, Massachusetts drivers can confidently navigate the insurance landscape. Remember, knowledge is your best ally when it comes to securing the most favorable insurance rates.
Frequently Asked Questions
What are the primary factors affecting auto insurance rates in Massachusetts?
The primary factors include your driving record, age, vehicle type, and credit score. Additionally, geographic location within Massachusetts can also significantly impact your rates.
How do Massachusetts auto insurance rates compare to the national average?
Massachusetts rates are generally higher than the national average, primarily due to state-specific regulations and higher population density in urban areas.
What types of auto insurance coverage are required by law in Massachusetts?
Massachusetts requires drivers to have Bodily Injury Liability, Property Damage Liability, Personal Injury Protection (PIP), and Uninsured Motorist Coverage.
Are there any discounts available for Massachusetts auto insurance?
Yes, discounts such as good driver discounts, multi-policy discounts, and student discounts are commonly available to help reduce your premium.
How can geographic location within Massachusetts affect insurance rates?
Living in urban areas with higher traffic density or neighborhoods with high theft rates can result in higher insurance premiums compared to rural areas.
What recent legislative changes have affected auto insurance rates in Massachusetts?
Recent legislative changes have focused on enhancing consumer protection and transparency, which may cause fluctuations in premium calculations.
What are some strategies to qualify for multiple discounts on auto insurance in Massachusetts?
Maintaining a clean driving record, bundling insurance policies, and installing safety features in your vehicle are effective strategies to qualify for multiple discounts.
